
Tax Law ✦ California
Tax Problems Don’t Fix Themselves. Neither Does Tax Planning.
Audits, back taxes, levies, unfiled returns, and the planning that keeps you out of that cycle in the first place. North Star Law Firm represents California taxpayers before the IRS, the Franchise Tax Board, the CDTFA, the EDD, the Office of Tax Appeals, and the U.S. Tax Court, and structures businesses, real estate, and transactions so the tax is right before the return is filed. Led by an attorney-CPA. Flat fees. Free consultation.
Overview
What does our tax practice cover?
Tax law at North Star runs on two tracks. Tax defense is representation against a government tax authority: the examination, collection, and appeals functions of the IRS and California’s agencies, and litigation when the agency gets it wrong. Tax planning is the work that happens before the return: choosing and structuring entities, timing transactions, and building real estate and business deals around the tax result. Both tracks are handled by the same attorney-CPA, which is the point.
- Tax defense: IRS and Franchise Tax Board audits, appeals, and collections
- CDTFA sales and use tax audits; EDD payroll tax and worker classification
- Offers in compromise with the IRS (I.R.C. § 7122) and the FTB (R&TC § 19443)
- Installment agreements (I.R.C. § 6159) and hardship status
- Penalty abatement: first-time abatement and reasonable cause
- Unfiled federal and California returns; substitute-for-return correction
- U.S. Tax Court petitions and Office of Tax Appeals cases
- Entity selection and S corporation planning under California’s franchise tax rules
- Real estate and investment tax strategy: 1031 exchanges, cost segregation, Prop. 19
- Business sale and M&A tax structuring: asset vs. stock, allocation, installment sales
Know Your Deadline
Which notice did you get, and how long do you have?
Federal and California notices run on different clocks, and the California ones are often shorter. Find your letter below and bring it to the free consultation; the notice code tells us most of what we need to know.
| Notice | Who sent it | What it means | Your window |
|---|---|---|---|
| CP14 / CP501 / CP503 | IRS | Balance-due bills; the collection clock is running | Respond before the next escalation |
| CP504 | IRS | Notice of Intent to Levy; the IRS can seize your state refund | Act now; the final notice is next |
| LT11 / Letter 1058 | IRS | Final Notice of Intent to Levy | 30 days to request a collection due process hearing (I.R.C. § 6330) |
| CP2000 | IRS | Proposed changes; reported income doesn’t match your return | 30 days to respond |
| Letter 3219 / CP3219 | IRS | Statutory Notice of Deficiency, the 90-day letter | 90 days to petition the U.S. Tax Court |
| Notice of Proposed Assessment | FTB | California income tax deficiency | 60 days to file a written protest (R&TC § 19041) |
| Notice of Action | FTB | FTB has ruled on your protest | 30 days to appeal to the Office of Tax Appeals (R&TC § 19045) |
| Notice of Determination | CDTFA | Sales and use tax deficiency | 30 days to petition for redetermination |
| Notice of Assessment | EDD | Payroll tax or worker misclassification assessment | 30 days to petition the CUIAB |
| Order to Withhold / Earnings Withholding Order | FTB | A levy on your bank or wages is already in motion | Call immediately; releases are possible but move fast |
Representation Matters
What changes the day you have representation?
The day we file a power of attorney (IRS Form 2848, FTB Form 3520), the agency is required to deal with us instead of you. The calls stop coming to your phone. We pull your IRS account transcripts through the practitioner line and your FTB account through MyFTB, and reconstruct exactly what each agency thinks you owe (tax, penalties, interest, and the assessment and collection statute dates that control your options) before anyone talks numbers.
Then the leverage shifts. Revenue officers and FTB collectors follow their own manuals; we know what those manuals let them accept. Collection alternatives are computed under the agency’s own financial standards, appeal rights are preserved at every step, and when the government is simply wrong, the case goes to the IRS Independent Office of Appeals, the Office of Tax Appeals, or the U.S. Tax Court, where taxpayers win more often than people think.
The IRS has 80,000 employees and the FTB has 6,000. You only need one advocate who knows both rulebooks.
How does tax defense work in California when both the IRS and the FTB are involved?
California is unusual: the Franchise Tax Board is one of the most aggressive state tax agencies in the country, and it shares information with the IRS in both directions. A federal audit adjustment must be reported to the FTB within six months (R&TC § 18622), and an FTB assessment often follows an IRS one automatically. The reverse is also true, which means a problem with one agency is rarely a problem with only one agency.
We handle both in one engagement. That means the federal audit or collection case and the California protest, appeal, or collection matter are worked together, with the same transcripts, the same financial statement, and one strategy, instead of two professionals giving you two different answers. The FTB’s tools are also different from the IRS’s: a twenty-year collection statute (R&TC § 19255), bank and wage orders issued without a court, driver’s license and professional license suspension for the largest balances (Bus. & Prof. Code § 494.5), and publication on the Top 500 delinquent taxpayer list. Each has a defense, and each has a deadline. Read more →
What about CDTFA sales tax audits and EDD payroll tax assessments?
Sales and use tax audits by the California Department of Tax and Fee Administration are records fights. The auditor tests your reported sales against bank deposits, purchase invoices, and, for restaurants and retailers, markup analysis and observation tests. If your records are thin, the CDTFA estimates, and it estimates high. As a CPA-led firm we rebuild the sales record from source documents, challenge the estimation method, and handle the petition for redetermination and the appeals conference that follow a Notice of Determination.
EDD assessments usually come from a worker classification audit: the EDD decides your independent contractors were employees under the ABC test of Labor Code § 2775 and assesses unemployment insurance, disability insurance, and personal income tax withholding on their pay, plus penalties. A petition to the California Unemployment Insurance Appeals Board must be filed within 30 days. We defend the classification where the facts support it, negotiate the assessment where they do not, and address the federal side (IRS Form SS-8 and Section 530 relief) at the same time. Read more →
Do I qualify for an offer in compromise?
You qualify to settle for less than you owe when your reasonable collection potential (net equity in assets plus a multiple of your monthly disposable income) is less than your balance. That is a math problem before it is a legal one, and it is exactly where an attorney-CPA earns the fee: we compute your RCP under the IRS’s own financial standards first, so you know whether an offer is realistic before applying.
California has its own program. The FTB accepts offers in compromise under R&TC § 19443, and the CDTFA under R&TC § 7093.5, each on its own forms and its own view of your ability to pay. When you owe both governments, the offers have to be sequenced and the financial statements have to be consistent, because each agency will see what you told the other. When an offer is not the right tool, an installment agreement or partial-pay installment agreement often is. Read more →
What if I can’t pay, but I don’t qualify for an offer?
An installment agreement under I.R.C. § 6159 stops levy action while it is pending and in place, and for balances under $50,000 the IRS will generally approve a streamlined plan without a full financial statement. Above that, or where the payment the IRS wants is more than you can afford, a partial-pay installment agreement or currently-not-collectible status is negotiated from your financial statement. The FTB offers installment agreements as well, generally over 60 months, and will release an Order to Withhold once one is in place.
The collection statute matters here. The IRS has ten years from assessment to collect (I.R.C. § 6502); an agreement that runs past that date is one the IRS will never fully collect. We build the plan around that date, not around the first number the collector suggests. Read more →
Can tax penalties be removed?
Frequently, yes. First-time abatement is available administratively from the IRS if you have a clean three-year compliance history. Beyond that, penalties can be abated for reasonable cause (illness, disaster, reliance on professional advice, records beyond your control) under the standards of I.R.C. § 6651 and related provisions. Interest on abated penalties falls away with them, so penalty work often shrinks a balance meaningfully.
The FTB applies a reasonable-cause standard too, and since 2022 it offers individuals a one-time abatement of late-filing and late-payment penalties under R&TC § 19132.5 for taxpayers with a clean four-year history. Its demand penalty (25 percent for ignoring a Demand for Tax Return) and its late-payment penalties stack quickly, and relief for those is a written request with documentation, far more likely to succeed when it is written by someone who has read the FTB’s own penalty reference chart. Read more →
What if I haven’t filed returns in years?
You are not the only one, and there is a well-worn path back. In most cases the IRS looks for the last six years of returns to consider you compliant. If the IRS filed substitute-for-return assessments for you under I.R.C. § 6020(b), those returns ignore your deductions, exemptions, and correct filing status, so filing accurate originals usually reduces the assessed balance, sometimes dramatically. The FTB does the same thing with its own Notice of Proposed Assessment based on federal or 1099 data, and the same fix applies.
As a CPA-led firm, we prepare and file the back returns, federal and California, and negotiate the resulting balances in one engagement. If California has never seen a return from you, we can also evaluate whether the FTB’s filing enforcement program or its voluntary disclosure program is the right door to walk through. Read more →
When does a tax case go to court?
When the agency is wrong and administrative appeals have not fixed it. A Statutory Notice of Deficiency gives you 90 days to petition the U.S. Tax Court, a prepayment forum where you contest the tax before paying it; miss the deadline and your options narrow dramatically. Phillip Zagotti is admitted to the U.S. Tax Court and handles cases from petition through trial, including the small tax case procedure for disputes under $50,000.
California’s equivalent is the Office of Tax Appeals, an independent body that hears appeals from FTB and CDTFA decisions. An appeal must be filed within 30 days of an FTB Notice of Action, and the OTA proceeding is a written and oral case that is won or lost on the record you build. We build the record from the protest stage forward so the OTA appeal is ready if it is needed. Read more →
Which entity should my California business be?
California punishes the wrong answer more than most states. Every LLC pays the $800 annual franchise tax (R&TC § 17941) plus a gross-receipts fee that starts at $250,000 of revenue (R&TC § 17942), whether or not the LLC is profitable. An S corporation pays a 1.5 percent tax on net income (R&TC § 23802) with the same $800 minimum, but its owners can often reduce self-employment tax with a reasonable salary and distribution structure. A C corporation pays 8.84 percent and is rarely right for a closely held business unless the owners are planning for qualified small business stock treatment on a future sale.
The right answer depends on your revenue, your margin, how many owners there are, whether you will sell the business, and whether California’s elective pass-through entity tax (the workaround for the federal SALT cap) makes sense for you. We run the numbers under each structure before you file the formation documents, and we handle the formation itself through our business and contract law practice. Read more →
How do I lower the tax on real estate and investments?
Real estate is where California owners have the most room to plan and the most to lose from not planning. A Section 1031 exchange defers the gain on investment property, but only if the identification and closing deadlines are met to the day and the exchange is structured before escrow closes. Cost segregation accelerates depreciation on commercial and rental property. Proposition 19 changed the rules for passing property to children while keeping the parent’s property tax base, and most families who assumed the old exclusion still applies are in for an unpleasant reassessment.
We also handle the questions that come up when property changes hands inside a family or a trust: the basis step-up at death under I.R.C. § 1014, community property treatment that gives both halves a step-up, and the interaction between a living trust and the county assessor. That work overlaps with our trusts and estates practice, and it is why having both under one roof matters. Read more →
How should I structure the sale of my business?
Whether you sell assets or stock, how the price is allocated among asset classes under I.R.C. § 1060, whether an installment sale spreads the gain, and whether a seller-financed note or an earnout is taxed as capital gain or ordinary income are decisions worth real money, and they are made before the letter of intent is signed, not after. For a buyer, the same decisions set the basis you will depreciate for the next fifteen years.
California adds its own layer: a full 13.3 percent top rate on capital gains, no preferential rate, and the question of whether an installment note is taxable in California when the seller has already moved out of state. We negotiate the tax terms of the deal alongside the business terms and draft or review the purchase agreement through our transactional practice. Read more →
The Attorney-CPA Difference
Tax is a numbers fight and a law fight. We fight both.
- IRS and FTB transcripts analyzed like a CPA: the real balance, the real deadlines, the collection statute expiration date
- Negotiation and litigation handled like a lawyer: CDP hearings, Appeals conferences, OTA appeals, Tax Court petitions
- Planning built on the same knowledge: we know what gets audited because we defend the audits
- Attorney-client privilege protecting what you tell us
- Flat fee quoted in writing before you commit, with payment plans available
Proof, In Print
He wrote the book on tax defense. Literally.
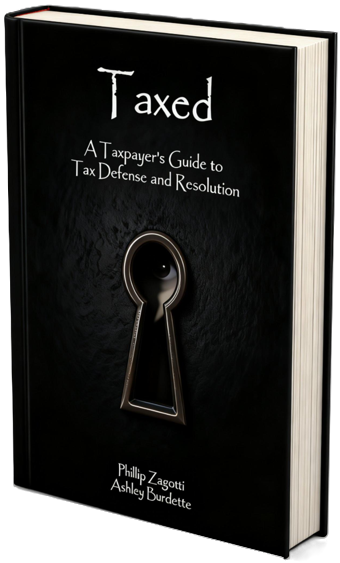
Phillip Zagotti co-authored Taxed: A Taxpayer’s Guide to Tax Defense and Resolution with Ashley Burdette, a plain-English guide to audits, IRS collections, and the resolution tools described on this page. If you want to understand your situation before you call anyone, or you’d rather work the problem yourself first, start with the book. When you decide you want a professional in your corner, the consultation is free.
Questions & Answers
Tax questions Californians ask us
How fast can a levy or wage garnishment be stopped?
Sometimes within days. Once a power of attorney is on file we can contact the IRS or the FTB directly, request a hold on collection, and negotiate a resolution. If an IRS collection due process window is still open under I.R.C. § 6330, filing the request generally stops levy action while the hearing is pending. FTB Orders to Withhold are released once an installment agreement or hardship determination is in place.
I got a Notice of Deficiency (90-day letter). What now?
Do not ignore it. You have 90 days to petition the U.S. Tax Court, a prepayment forum where you contest the tax before paying it. The deadline is jurisdictional; miss it and the tax is assessed. Call immediately.
The FTB says I owe tax for a year I didn’t even live in California. Can they do that?
They can assess it, and they will if California-source income or a California address shows up in their data. Whether you were a resident is a facts-and-circumstances question under R&TC § 17014 and the FTB’s own residency factors, and it is one of the most litigated issues before the Office of Tax Appeals. A protest within 60 days of the Notice of Proposed Assessment preserves the fight.
Do you handle tax planning for people who are not in trouble?
Yes, and it is a large part of the practice. Entity selection, S corporation compensation planning, real estate strategy, and business sale structuring are all planning engagements with a flat fee and a written memo at the end. The best time to talk to a tax attorney is before the transaction closes.
Stop letting the tax agency set the terms.
A free, confidential case review with an attorney-CPA, and a flat fee in writing before you commit.